
Summer 2026

—Adrian G. Davies, CFA – President
There seems to be virtually insatiable demand for artificial intelligence (AI) and the compute capacity that powers it. The industry has an “if you build it, they will come” aspect to it: Any additional capacity is readily absorbed. Demand is coming from much more than just large language models (LLMs), graphics engines, and AI agents. Autonomous driving and robotics (physical AI) are two other large applications, and there are many more. The AI investment thesis used to be simple: “AI will grow.” Now, the investment thesis is more complicated, and that complexity isn’t attracting new investors. LLMs are proliferating, with greater competition resulting in pricing pressure. Lower LLM prices may stimulate even more demand, while AI service providers and their users will still have to pay for compute capacity. We will see if other AI applications face similar competitive pressures.
Builders of AI infrastructure face all manner of obstacles in bringing capacity to market, from public opposition and regulation to water and energy supply constraints. These bottlenecks restricting the pace at which new compute capacity comes online might be unexpected blessings for the industry, assuring that what supply does get built remains in high demand.
Another important question is how all this data center construction will be financed. The five largest hyperscalers[1] are looking to spend about $800 billion on data centers this year, rising to $1 trillion next year (see Table 1). Beyond the top hyperscalers, a cohort of third parties including private equity are also looking to get in on the action, investing alongside the hyperscalers and also building their own data centers. For 2026, the economy is benefitting not so much from an AI boom, but rather a data center construction boom. Since imports do not contibute to GDP however, and more than half of these capital expenditures are being spent on imported electronic equipment, the impact on US GDP is less than what one might otherwise expect.
Table 1. Top Five Hyperscaler Capital Expenditures

Source: FactSet, FactSet consensus estimates
The hyperscalers generate formidable cash flow from their core business operations, now piling it into data center construction. They are borrowing large sums of money and raising equity in order to build more and bigger data centers than what their internal cash flow can support. The hyperscalers probably aren’t expecting to continue these buildouts at a $1 trillion rate ad infinitum, although much will depend on the investment returns they are able to generate. As long as demand for data processing exceeds supply, compute providers can set their prices. If capacity catches up with demand, and it isn’t clear when or if it will, competition among providers may reduce investment returns.
The capital requirements are a lot for the markets to absorb. JP Morgan estimates that hyperscalers will raise $1.5 trillion in investment-grade debt over the next five years, raising still more with additional debt instruments.[2] The massive supply of debt issuance from data centers and AI providers, particularly when coupled with the supply of Treasurys stemming from our country’s burgeoning federal deficit, is having difficulty finding investors. Supply relative to demand sets the price, so the debt will find investors, but at lower prices and higher yields than current market rates. Indeed, the 10-year US Treasury yield rose 0.27 percentage points during the first six months of the year, and has risen further since. Interest rates may continue rising as more debt issuance comes to market.
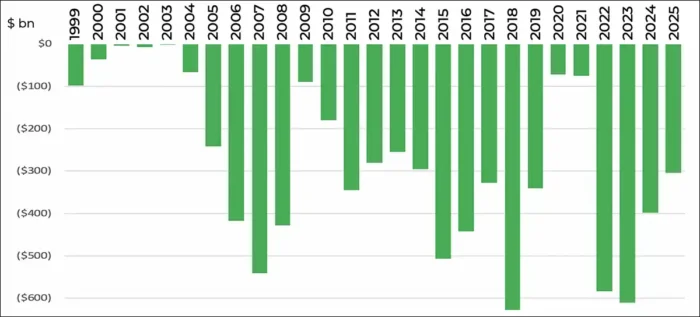
Because they’ve been investing all of their cash flow in data centers, hyperscalers have reduced their share repurchases to a virtual standstill. Over the last 20 years, publicly traded US companies have retired more shares through buybacks than they have issued (see Figure 1). That could change this year with all of the fundraising required to pay for data centers and AI labs, particularly if one includes shares coming to marketfrom private investors following the public offering of SpaceX, the anticipated offering of Anthropic, and other issuances. Through the first half of 2026, the hyperscalers raised $159 billion in debt and $90 billion in new equity. While the stock market is not far off its all-time high at the time of this writing, demand for capital could yet drive the cost of equity capital up as well, meaning stock prices would fall. That construction constraints might limit data center buildout would prove to be a blessing not only for data center investment returns, but for shareholders and for anyone impacted by higher interest rates.
Figure 1. US Net Equity Issuance by Year
Source: Federal Reserve
This Is Not 2000
Every year or so there’s some small subset of stocks that captures investors’ imagination and ends up soaring to sky-high prices. Prices overshooting reasonable valuations is a fairly regular feature of the market. In the last few years, we’ve seen mini-bubbles in the stocks of special-purpose acquisition vehicles, electric vehicle manufacturers (other than Tesla), cryptocurrency exchanges, buy now pay later businesses, financial technology businesses, battery technology developers, optical transceivers manufacturers, cannabis growers, uranium miners, and quantum computing developers, to cite some examples. There’s always a compelling argument for buying these stocks—some fundamental reason to expect strong stock returns—but then investors fail to anticipate competition, overlook some bottlenecks to growth, or at least don’t appreciate how much enthusiasm has been built into elevated stock prices. The stocks ultimately fall back to earth. Typically the industry such stocks represent is small enough that there aren’t significant consequences for the broader stock market or the economy.
AI has certainly captured investors’ imagination, with enthusiasm for the stocks appearing to wane now. To be sure, there are numerous smaller capitalization AI-themed stocks that became overextended. But AI happens to be a very big theme, dominated by very large capitalization stocks. If investors were to become less enamored with AI stocks, the group is large enough to drive the S&P 500 Index lower. The Magnificent Seven stocks,[3] which comprise about 33% of the S&P 500 Index, and which have all become some form of AI investment story, have collectively underperformed since the beginning of the year.
Despite their underperformance however, the S&P 500 Index has continued to approach new highs. Within large capitalization AI-related businesses, investor interest has shifted from the Magnificent Seven to semiconductor memory stocks like Micron and Sandisk. These latter stocks recently traded at modest multiples of around 10x earnings, mostly because their earnings exploded higher by as much or more than their share prices. The stocks are even cheaper now. There could always be further upside in memory, but historically the stocks have been very cyclical. Those low price-to-earnings multiples could be deceptive, as earnings forecasts could easily fall from here.
Investor attention may simply shift again to the next set of shiny objects, to the detriment of the current AI-themed beneficiaries. While valuations of the Magnificent Seven stocks could always be lower, we do not see their stock valuations “bursting” the way the technology bubble of 2000 did. There remain new applications for AI to be tapped and massive potential for growth as the technology improves and becomes cheaper. In 2000, the internet promised and subsequently delivered on similar growth potential, with the key differences now being that the Magnificent Seven stocks are supported by large existing businesses that provide strong free cash flow, and, with one exception, they do not trade anywhere near the same levels of overvaluation that comparable stocks traded for during the internet bubble.
Tesla is the only Magnificent Seven stock currently trading above 35x earnings. For the most part, the Magnificent Seven stocks trade at multiples that can be justified on the basis of future earnings growth. Despite waning sentiment, we believe the fundamentals of the Magnificent Seven stocks will stay strong, and we are looking for them to generate reasonable returns from their data center investments. Our main concern, however, is that the massive demand for capital is driving up the costs of both equity and debt capital. Higher capital costs seem likely to put a damper on market valuations generally.
At the risk of repeating ourselves, we are not focused on short-term performance. We are focused on managing diversified portfolios of high-quality companies that will stand the test of time through numerous market environments. In addition to believing AI-themed stocks will continue to generate healthy returns, we further believe there are plenty of opportunities outside of AI which have been overlooked. As we have been suggesting for some time, it seems to be their turn to rise.
We are further hopeful that AI is accelerating economic growth. AI can speed up many manufacturing and services processes. It’s making new types of work possible, and can enable technological breakthroughs. There will be winners and losers. Productivity from AI could disrupt the job market, but we expect AI will destroy jobs at a pace that can be offset by the creation of new jobs. On balance, our economy is likely to be more productive, more dynamic, and more robust for adopting AI. A broader group of stocks will likely benefit from the fruits of AI. At the same time, policymakers may be challenged to see to it that the benefits of AI’s economic advancement are broadly distributed.
[1] Amazon, Microsoft, Alphabet, Meta, and Oracle.
[2] Herman Chan and Ravi Chelluri, “Trading Lifts Fees; Wealth & Banking Anchor,” Bloomberg Intelligence, 12/12/25.
[3] Nvidia, Alphabet, Apple, Microsoft, Amazon, Meta Platforms, and Tesla.